PRINCIPLES OF DOCUMENT STORAGE
15:01:4727/05/2021
In saving documents, there are no standards or principles at all. But saving it correctly and making it easy to find is something that gives accountants a headache every day. CPA has collected the following tips, hoping to help accountants work more smoothly.
Principles of how to save documents that most accountants should follow:
At any time a transaction occurs, save all documents arising from that transaction in one place (ie there is 1 recording document and all original documents attached). That is, we open the file to save the document according to the name of the recording document (For example, file named Payment Voucher, File named Receipt Voucher, File named Receivable Accounting Voucher, File named Payable Accounting Voucher, File named Warehouse Receipt Voucher). , Warehouse Delivery Note File, Other accounting files... Each month is 1 file, every 12 months is 12 files).
Saving accounting documents is an extremely important step, because if you do not do this step well, later on, finding and comparing data between books and documents will be very difficult, and you will also have to find documents to restore them. Serving the tax authorities and serving the audit team. So the problem of saving documents is that each unit has a different way of saving, no unit saves the same. Below is a way to save documents for your reference and application when going to work.
At any time a transaction occurs, save all documents arising from that transaction in one place (ie there is 1 recording document and all original documents attached). That is, we open the file to save the document according to the name of the recording document (For example, file named Payment Voucher, File named Receipt Voucher, File named Receivable Accounting Voucher, File named Payable Accounting Voucher, File named Warehouse Receipt Voucher). , Warehouse Delivery Note File, Other accounting files... Each month is 1 file, every 12 months is 12 files).
Saving accounting documents is an extremely important step, because if you do not do this step well, later on, finding and comparing data between books and documents will be very difficult, and you will also have to find documents to restore them. Serving the tax authorities and serving the audit team. So the problem of saving documents is that each unit has a different way of saving, no unit saves the same. Below is a way to save documents for your reference and application when going to work.
✿✿HOW TO SAVE ACCOUNTING DOCUMENTS:
- 12 Receipt files: sandwiched with copy 3 of the output VAT invoice and goods handover record, accompanied by other related documents (Reimbursement request form, Capital contribution record)
- 12 files: Payment slip: clip with purchase invoice (remember to clip photo of invoice), Handover record, deposit slip into bank account, advance request, Payment request form, ID card and other documents other related
- Separate bank file for each bank: The bank subsidiary book of each bank is placed first, followed by the bank's Debit and Credit Notices accompanied by photocopied original documents (for example, financial purchase invoices). input) or original table to explain each banking operation
-12 files of warehouse receipt (goods or finished products): clip with the purchase invoice of the goods (remember to clip the photocopy of the invoice), accompanied by the goods handover record, economic contract (if any arises). times if any or orders, price quotes...)
- 12 Receipt files: sandwiched with copy 3 of the output VAT invoice and goods handover record, accompanied by other related documents (Reimbursement request form, Capital contribution record)
- 12 files: Payment slip: clip with purchase invoice (remember to clip photo of invoice), Handover record, deposit slip into bank account, advance request, Payment request form, ID card and other documents other related
- Separate bank file for each bank: The bank subsidiary book of each bank is placed first, followed by the bank's Debit and Credit Notices accompanied by photocopied original documents (for example, financial purchase invoices). input) or original table to explain each banking operation
-12 files of warehouse receipt (goods or finished products): clip with the purchase invoice of the goods (remember to clip the photocopy of the invoice), accompanied by the goods handover record, economic contract (if any arises). times if any or orders, price quotes...)
- 12 files of delivery note (goods or finished products): attached to the 2nd copy of the sales invoice, remember to include the goods handover record
-12 files for warehousing of raw materials: Clip the receipt for warehousing of raw materials together with the purchase financial invoice, handover record and economic contract if it arises once or for an order.
-If the company has import and export, save 12 files as the import customs declaration with REF to other relevant documents (for example, warehouse receipt or contract...) and 12 files of export customs documents. Type REF to other relevant documents (eg contract, delivery note, handover record...) to facilitate future checking and comparison.
-1 File stores the fixed asset card along with the original documents (i.e. live signed documents) that form that asset. Remember that each asset is a fixed asset card.
-Payroll file (12 payrolls): attached to the payroll is the timesheet. Salary calculation slip of each person with signature. At the same time, the bonus calculation file (accompanied by reward decisions...)
-12 files for warehousing of raw materials: Clip the receipt for warehousing of raw materials together with the purchase financial invoice, handover record and economic contract if it arises once or for an order.
-If the company has import and export, save 12 files as the import customs declaration with REF to other relevant documents (for example, warehouse receipt or contract...) and 12 files of export customs documents. Type REF to other relevant documents (eg contract, delivery note, handover record...) to facilitate future checking and comparison.
-1 File stores the fixed asset card along with the original documents (i.e. live signed documents) that form that asset. Remember that each asset is a fixed asset card.
-Payroll file (12 payrolls): attached to the payroll is the timesheet. Salary calculation slip of each person with signature. At the same time, the bonus calculation file (accompanied by reward decisions...)
- The Prepaid Expense Allocation Table file is designed to have a column of document numbers to facilitate future document lookup (Includes 12 tables for 12 months or make 1 allocation table with 12 columns from January to December )
- Fixed asset depreciation allocation table file (Includes 12 tables for 12 months or make 1 allocation table with 12 columns from January to December)
- Other accounting slips.
-1 File to save original purchase and sale invoices to coincide with monthly or quarterly VAT declarations to facilitate future tax audits and inspections
Note: the way the documents are arranged is that the DOCUMENTS THAT THE ACCOUNTANT MADE (i.e. the documents used to record books are arranged first, then the original documents are clamped) are arranged first, followed by the original documents for explanation.
- Fixed asset depreciation allocation table file (Includes 12 tables for 12 months or make 1 allocation table with 12 columns from January to December)
- Other accounting slips.
-1 File to save original purchase and sale invoices to coincide with monthly or quarterly VAT declarations to facilitate future tax audits and inspections
Note: the way the documents are arranged is that the DOCUMENTS THAT THE ACCOUNTANT MADE (i.e. the documents used to record books are arranged first, then the original documents are clamped) are arranged first, followed by the original documents for explanation.
Tin cùng chuyên mục
CÔNG VĂN 8472/CT-QLNT: THUẾ TNCN 2% VÀ LỆ PHÍ TRƯỚC BẠ 0,5% KHI CHUYỂN NHƯỢNG BẤT ĐỘNG SẢN
Ngày 06/11/2026, Cục Thuế ban hành Công văn số 8472/CT-QLNT hướng dẫn thuế thu nhập cá nhân và lệ phí...
11/11/2026
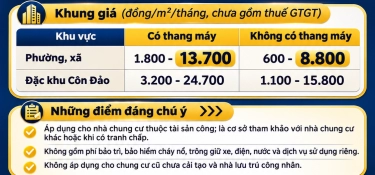
TP. HCM BAN HÀNH KHUNG GIÁ MỚI DỊCH VỤ QUẢN LÝ VẬN HÀNH NHÀ CHUNG CƯ, ÁP DỤNG TỪ 25/11/2026
Ngày 07/11/2026, UBND TP. HCM ban hành Quyết định số 96/2026/QĐ-UBND quy định khung giá dịch vụ quản lý...
11/11/2026
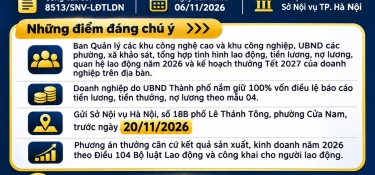
HÀ NỘI: BÁO CÁO TÌNH HÌNH TIỀN LƯƠNG, THƯỞNG TẾT 2027 TRƯỚC 20/11/2026
Ngày 06/11/2026, Sở Nội vụ TP. Hà Nội ban hành Công văn số 8513/SNV-LĐTLDN về việc báo cáo tình hình lao...
11/11/2026
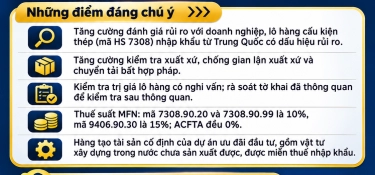
CẤU KIỆN THÉP, NHÀ TIỀN CHẾ NHẬP KHẨU: HẢI QUAN SIẾT KIỂM TRA TRỊ GIÁ, XUẤT XỨ
Ngày 06/11/2026, Cục Hải quan ban hành Công văn số 23969/CHQ-NVTHQ về quản lý rủi ro, kiểm tra xuất xứ và...
11/11/2026
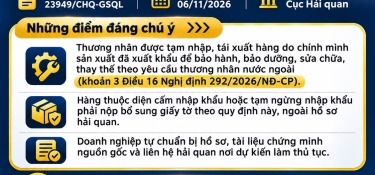
TẠM NHẬP HÀNG ĐÃ XUẤT KHẨU ĐỂ BẢO HÀNH, SỬA CHỮA: CHUẨN BỊ HỒ SƠ THẾ NÀO?
Ngày 06/11/2026, Cục Hải quan ban hành Công văn số 23949/CHQ-GSQL hướng dẫn thủ tục hải quan và tài liệu...
11/11/2026
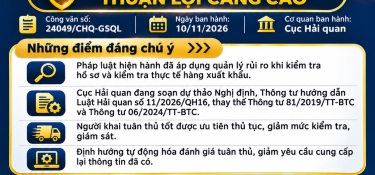
CỤC HẢI QUAN TRẢ LỜI KIẾN NGHỊ ĐƠN GIẢN HÓA KIỂM TRA HÀNG XUẤT KHẨU
Ngày 10/11/2026, Cục Hải quan ban hành Công văn số 24049/CHQ-GSQL trả lời kiến nghị của doanh nghiệp về...
11/11/2026
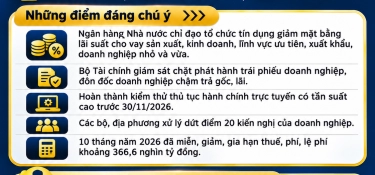
NGHỊ QUYẾT 353/NQ-CP: CHÍNH PHỦ YÊU CẦU TIẾP TỤC GIẢM LÃI SUẤT CHO VAY NHỮNG THÁNG CUỐI NĂM 2026
Ngày 06/11/2026, Chính phủ ban hành Nghị quyết số 353/NQ-CP phiên họp Chính phủ thường kỳ tháng 10/2026,...
11/11/2026
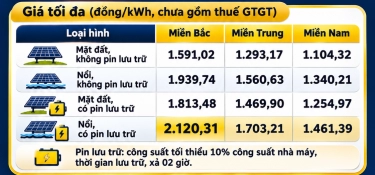
QUYẾT ĐỊNH 2946/QĐ-BCT: KHUNG GIÁ PHÁT ĐIỆN MẶT TRỜI NĂM 2026 CAO NHẤT 2.120,31 ĐỒNG/kWh
Ngày 05/11/2026, Bộ Công Thương ban hành Quyết định số 2946/QĐ-BCT phê duyệt khung giá phát điện loại...
11/11/2026
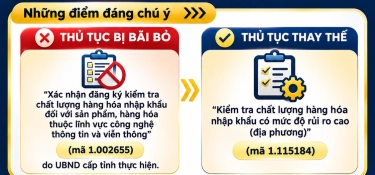
BÃI BỎ THỦ TỤC XÁC NHẬN ĐĂNG KÝ KIỂM TRA CHẤT LƯỢNG HÀNG NHẬP KHẨU CÔNG NGHỆ THÔNG TIN, VIỄN THÔNG
Ngày 03/11/2026, Bộ Khoa học và Công nghệ ban hành Quyết định số 4331/QĐ-BKHCN công bố thủ tục hành...
11/11/2026
THÔNG TƯ 57/2026/TT-NHNN: QUY TRÌNH GIÁM SÁT PHÒNG, CHỐNG RỬA TIỀN ÁP DỤNG TỪ 01/12/2026
Ngày 30/10/2026, Ngân hàng Nhà nước ban hành Thông tư số 57/2026/TT-NHNN quy định trình tự, thủ tục giám...
11/11/2026
REGISTER FOR WORKERSREGISTER OF RECRUITMENT
Most Viewed News
[HỘI THẢO ONLINE ]: CHI PHÍ LƯƠNG ĐƯỢC TRỪ KHI TÍNH THUẾ TNDN THEO NGHỊ ĐỊNH 320/2025/NĐ-CP
15/01/2026
Năm 2025 khép lại với những thay đổi chóng...
"TOP 20 EXCELLENT ENTERPRISES IN 2024" CPA HO CHI MINH CITY AFFIRMS ITS LEADING POSITION IN THE ACCOUNTING AND AUDITING INDUSTRY
21/08/2024
In a year full of changes, CPA HCM Audit &...
CPA HCM Training Academy continues to welcome more than 500 students from Ho Chi Minh City College of Economics.
16/06/2023
What benefits will you get from this course?
FOR THE FIRST TIME SIU STUDENTS LEARN FORMAL ACCOUNTING PRACTICE IN A BUSINESS ENVIRONMENT
05/04/2024
CPA HCM AUDIT & CONSULTING COMPANY LIMITED is...
SHORT THE ROAD TO SUCCESS WITH THE COURSE "GENERAL ACCOUNTING"
08/05/2024
You have accounting knowledge but feel it is not...
© All rights and copyrights belong to CPA HCM Audit and Advisory Company Limited Designed by
IMS