CONSTRUCTION ACCOUNTING NOTES - CONSTRUCTION AND INSTALLATION
21:00:4201/06/2021
Necessary notes for accountants in the construction industry
+ Error 1: The project has been accepted, but due to some reasons we cannot issue an invoice. For example: Party A hasn't paid yet so the boss won't let it go. With this error, we will have our revenue and VAT returned at the time of acceptance.
+ Error 2: The input of raw materials and labor does not match the estimate, because the materials and labor are loaded by the accountant based on emotion. And it leads to:
- The cost of raw materials included is higher than the total level of raw materials in the total budget items of the estimate.
- Salary costs are higher than the total labor level in the total budget items of the old estimate
- General production costs included are higher than the total general production costs in the total budget items of the estimate.
- The cost of construction machines included is higher than the total cost of construction machines in the total cost of each item in the estimate.
+ Error 3: Raw materials are taken after the acceptance date but are still included as expenses when there are not enough procedures to protect them. To protect you need:
- Contract
- Goods handover record "The date on the record is the day before acceptance and the record is numbered.
+ Error 2: The input of raw materials and labor does not match the estimate, because the materials and labor are loaded by the accountant based on emotion. And it leads to:
- The cost of raw materials included is higher than the total level of raw materials in the total budget items of the estimate.
- Salary costs are higher than the total labor level in the total budget items of the old estimate
- General production costs included are higher than the total general production costs in the total budget items of the estimate.
- The cost of construction machines included is higher than the total cost of construction machines in the total cost of each item in the estimate.
+ Error 3: Raw materials are taken after the acceptance date but are still included as expenses when there are not enough procedures to protect them. To protect you need:
- Contract
- Goods handover record "The date on the record is the day before acceptance and the record is numbered.
+ Error 4: I see a lot of companies with CTrinh have stopped construction but still calculate time and salary and still include costs, or I see some companies have time and salary calculation but no one signs. Even still depreciate and allocate construction machinery costs.
- The remuneration of the Board of Directors for members of the Board of Directors must be accompanied by a meeting minutes of the Board of Directors agreeing to appoint those members to directly participate in the operations of the enterprise or if it is a concurrent remuneration of a member of the Board of Directors. should be added to the salary to rationalize.
+ Error 5: Not separately tracking the costs of each project, raw materials, labor, and production are aggregated into one at the end of the month without distinguishing which project it belongs to, causing tax to ask if it is not. know which project it belongs to.
+ Error 6: With the cost of construction machines, almost small companies do not have oil norms for machine shifts and do not have vehicle mobilization schedules.
+ Error 7: The food bill the bosses brought home did not come with a bill. Or there is a case where the boss has a receipt for buying supplies from a supermarket...the boss buys it but brings it back to the accountant for tax declaration and is disbursed, not accepting the cost and deducting VAT.
- The remuneration of the Board of Directors for members of the Board of Directors must be accompanied by a meeting minutes of the Board of Directors agreeing to appoint those members to directly participate in the operations of the enterprise or if it is a concurrent remuneration of a member of the Board of Directors. should be added to the salary to rationalize.
+ Error 5: Not separately tracking the costs of each project, raw materials, labor, and production are aggregated into one at the end of the month without distinguishing which project it belongs to, causing tax to ask if it is not. know which project it belongs to.
+ Error 6: With the cost of construction machines, almost small companies do not have oil norms for machine shifts and do not have vehicle mobilization schedules.
+ Error 7: The food bill the bosses brought home did not come with a bill. Or there is a case where the boss has a receipt for buying supplies from a supermarket...the boss buys it but brings it back to the accountant for tax declaration and is disbursed, not accepting the cost and deducting VAT.
- Electricity and water costs for borrowed offices (not rented offices) but not under the company's name. Therefore, it is necessary to rationalize by renting an office at a low price and paying taxes if the electricity and water costs are large.
+ Error 8: Too much negative cash fund, there is no negative cash balance, negative bank deposits. Or collect cash and record debt, buy debt and record cash collection. This man's beard sticks to that woman's chin.
- If you have a lot of cash and borrow money from the bank, you should not accept the payment of the loan.
+ Error 9: Loans from individuals that exceed 150% of the basic interest rate prescribed by the State Bank will be eliminated, so it is necessary to rationalize by increasing the loan principal to reduce interest rates down.
+ Error 10: In case of signing a contract to purchase raw materials without the unit having a warehouse and writing a one-time invoice at the end of the month with a large value, the payment must be accompanied by additional detailed documents. Additional information such as: delivery note from the seller each time the unit picks up goods, a list of each day of receipt of goods signed by the seller and confirmed by the buyer. . . .then the cost is reasonable.
+ Error 11: It's about the books
- There is no summary table of debts and detailed debts.
+ Error 8: Too much negative cash fund, there is no negative cash balance, negative bank deposits. Or collect cash and record debt, buy debt and record cash collection. This man's beard sticks to that woman's chin.
- If you have a lot of cash and borrow money from the bank, you should not accept the payment of the loan.
+ Error 9: Loans from individuals that exceed 150% of the basic interest rate prescribed by the State Bank will be eliminated, so it is necessary to rationalize by increasing the loan principal to reduce interest rates down.
+ Error 10: In case of signing a contract to purchase raw materials without the unit having a warehouse and writing a one-time invoice at the end of the month with a large value, the payment must be accompanied by additional detailed documents. Additional information such as: delivery note from the seller each time the unit picks up goods, a list of each day of receipt of goods signed by the seller and confirmed by the buyer. . . .then the cost is reasonable.
+ Error 11: It's about the books
- There is no summary table of debts and detailed debts.
- There is no detailed raw materials book, no summary table of import and export inventory.
- Assets purchased without invoices or documents are still depreciated and allocated.
- Failure to pay license tax on time will result in late payment penalty.
- Failure to pay VAT and CIT on time with late payment penalty.
AND IF YOU WANT TO BE ACCURATE, REMEMBER TO GO TO CPA HCM!!!
- Assets purchased without invoices or documents are still depreciated and allocated.
- Failure to pay license tax on time will result in late payment penalty.
- Failure to pay VAT and CIT on time with late payment penalty.
AND IF YOU WANT TO BE ACCURATE, REMEMBER TO GO TO CPA HCM!!!
Tin cùng chuyên mục
CÔNG VĂN 8871/CT-QLNT: KHOẢN THU KHÔNG LIÊN QUAN BÁN HÀNG KHÔNG PHẢI LẬP HÓA ĐƠN ĐIỆN TỬ
Ngày 18/11/2026, Cục Thuế ban hành Công văn số 8871/CT-QLNT trả lời Thuế tỉnh Thái Nguyên: cơ sở kinh...
20/11/2026
CÔNG VĂN 24185/CHQ-NVTHQ: NƯỚC GIẢI KHÁT CÓ ĐƯỜNG TRÊN 5G/100ML CHỊU THUẾ TTĐB, KHÔNG ĐƯỢC GIẢM THUẾ GTGT
Ngày 12/11/2026, Cục Hải quan ban hành Công văn số 24185/CHQ-NVTHQ hướng dẫn chính sách thuế đối với...
20/11/2026
CÔNG VĂN 24424/CHQ-NVTHQ: THÁP ĐIỆN GIÓ NHẬP KHẨU TẠO TÀI SẢN CỐ ĐỊNH CÓ ĐƯỢC MIỄN THUẾ CHỐNG BÁN PHÁ GIÁ?
Ngày 18/11/2026, Cục Hải quan ban hành Công văn số 24424/CHQ-NVTHQ trả lời vướng mắc về thuế chống bán...
20/11/2026
CÔNG VĂN 8726/CT-QLNT: CHỦ SỞ HỮU HƯỞNG LỢI VÀ GIAO DỊCH LIÊN KẾT XÁC ĐỊNH THEO QUY ĐỊNH NÀO?
Ngày 13/11/2026, Cục Thuế ban hành Công văn số 8726/CT-QLNT trả lời kiến nghị của một công ty luật về...
19/11/2026
HÀNG KHÔNG VÀO NỘI ĐỊA VIỆT NAM KHÔNG CHỊU THUẾ GTGT: BÁN HÀNG TRONG KHO NGOẠI QUAN VÀ BÁN QUA SÀN NƯỚC NGOÀI
Thuế thành phố Hà Nội (Công văn số 52537/HAN-QLDN3 ngày 27/10/2026) và Thuế cơ sở 6 thành phố Hà Nội...
19/11/2026
CÔNG VĂN 52607/HAN-QLDN4: AI LẬP HÓA ĐƠN, AI NỘP THUẾ GTGT KHI THU PHÍ KHÔNG DỪNG TẠI BẾN XE, BÃI ĐỖ?
Ngày 27/10/2026, Thuế thành phố Hà Nội ban hành Công văn số 52607/HAN-QLDN4 hướng dẫn việc lập hóa đơn...
19/11/2026
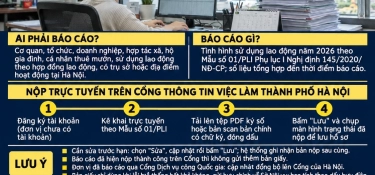
CÔNG VĂN 8865/SNV-VLATLĐ: DOANH NGHIỆP TẠI HÀ NỘI BÁO CÁO SỬ DỤNG LAO ĐỘNG NĂM 2026 TRƯỚC 05/12
Ngày 17/11/2026, Sở Nội vụ thành phố Hà Nội ban hành Công văn số 8865/SNV-VLATLĐ về việc báo cáo tình...
19/11/2026
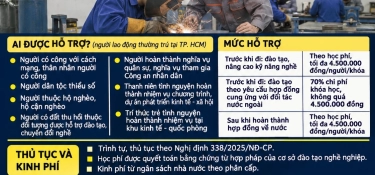
NGHỊ QUYẾT 92/2026/NQ-HĐND: LAO ĐỘNG TP. HCM ĐI LÀM VIỆC Ở NƯỚC NGOÀI ĐƯỢC HỖ TRỢ HỌC NGHỀ ĐẾN 4.500.000 ĐỒNG
Ngày 30/10/2026, HĐND Thành phố Hồ Chí Minh ban hành Nghị quyết số 92/2026/NQ-HĐND quy định hỗ trợ đào...
19/11/2026
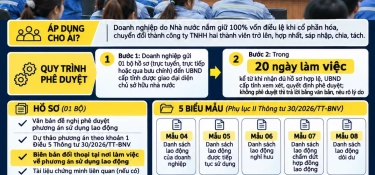
QUYẾT ĐỊNH 1405/QĐ-BNV: THỦ TỤC PHÊ DUYỆT PHƯƠNG ÁN SỬ DỤNG LAO ĐỘNG KHI CƠ CẤU LẠI DOANH NGHIỆP 100% VỐN NHÀ NƯỚC
Ngày 13/11/2026, Bộ Nội vụ ban hành Quyết định số 1405/QĐ-BNV về thủ tục phê duyệt phương án sử...
19/11/2026
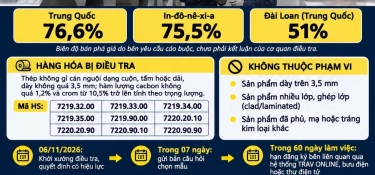
QUYẾT ĐỊNH 2948/QĐ-BCT: ĐIỀU TRA CHỐNG BÁN PHÁ GIÁ THÉP KHÔNG GỈ CÁN NGUỘI NHẬP KHẨU
Ngày 06/11/2026, Bộ Công Thương ban hành Quyết định số 2948/QĐ-BCT khởi xướng điều tra chống bán phá...
19/11/2026
REGISTER FOR WORKERSREGISTER OF RECRUITMENT
Most Viewed News
[HỘI THẢO ONLINE ]: CHI PHÍ LƯƠNG ĐƯỢC TRỪ KHI TÍNH THUẾ TNDN THEO NGHỊ ĐỊNH 320/2025/NĐ-CP
15/01/2026
Năm 2025 khép lại với những thay đổi chóng...
"TOP 20 EXCELLENT ENTERPRISES IN 2024" CPA HO CHI MINH CITY AFFIRMS ITS LEADING POSITION IN THE ACCOUNTING AND AUDITING INDUSTRY
21/08/2024
In a year full of changes, CPA HCM Audit &...
CPA HCM Training Academy continues to welcome more than 500 students from Ho Chi Minh City College of Economics.
16/06/2023
What benefits will you get from this course?
FOR THE FIRST TIME SIU STUDENTS LEARN FORMAL ACCOUNTING PRACTICE IN A BUSINESS ENVIRONMENT
05/04/2024
CPA HCM AUDIT & CONSULTING COMPANY LIMITED is...
SHORT THE ROAD TO SUCCESS WITH THE COURSE "GENERAL ACCOUNTING"
08/05/2024
You have accounting knowledge but feel it is not...
© All rights and copyrights belong to CPA HCM Audit and Advisory Company Limited Designed by
IMS