INSTRUCTIONS FOR HANDLING ERRORS IN ELECTRONIC INVOICES WITH CQT CODE ACCORDING TO DECREE 123
22:19:3429/09/2022
CPA HCM guides customers in handling errors in electronic invoices with CQT codes according to Decree 123 through the article below!
CPA HCM guides customers in handling errors in electronic invoices with CQT codes according to Decree 123 through the article below!
CASES OF ERRORS
· Case 1: The seller discovers that the electronic invoice that has been issued with a code from the tax authority and has not been sent to the buyer has errors.
Processing instructions:
- Step 1: The seller shall notify the tax authority according to Form No. 04/SS-HDĐT Appendix IA (issued together with Decree No. 123/2020/ND-CP, referred to as 04/SS-HDĐT) about Cancellation of electronic invoices with codes created with errors. The tax authority cancels the electronic invoice that has been issued a code with errors stored on the tax authority's system.
- Step 2: Create a new electronic invoice then digitally sign it and send it to the tax authority to issue a new invoice code.
- Step 3: Return the correct invoice to the buyer.
Note:
The seller chooses Form No. 04/SS-HDĐT to notify the adjustment for each invoice with errors or notify the adjustment for many electronic invoices with errors, and send it to the tax authority at any time. but no later than the last day of the value-added tax declaration period for which the adjusted electronic invoice arises.
· Case 2: An electronic invoice with a tax authority code or an electronic invoice without a tax authority code sent to the buyer and the buyer or seller discovers that there are errors in the buyer's name and address but the code is not incorrect. Tax numbers and other contents are not incorrect.
Processing instructions:
- Step 1: The seller notifies the buyer that the invoice has errors.
- Step 2: The seller shall notify the tax authority about the electronic invoice with errors according to Form No. 04/SS-HDĐT Appendix IA (except in cases where the electronic invoice does not have the tax authority's code and has errors). The above mentioned invoice data has not been sent to the tax authority).
Note:
- The seller does not have to re-invoice.
- In case the issued electronic invoice has errors and the seller has handled it in the form of adjustment or replacement as prescribed in Point b, Clause 2, Article 19 of Decree No. 123/2020/ND-CP, then reissued the invoice. If the invoice continues to have errors, the seller will follow the method applied when handling the error for the first time..
- The seller chooses Form No. 04/SS-HDĐT to notify the adjustment for each invoice with errors or notify the adjustment for many electronic invoices with errors, and send it to the tax authority at any time. but no later than the last day of the value-added tax declaration period for which the adjusted electronic invoice arises.
· Case 3: An electronic invoice with a tax authority code or an electronic invoice without a tax authority code has been sent to the buyer and the buyer or seller discovers that there is an incorrect tax code or an error in the amount recorded on the invoice. , wrong tax rate, tax amount or goods listed on the invoice are not of the correct specifications and quality.
Processing instructions:
Depending on the agreement, NTT chooses to handle the matter in the following two ways:
Method 1: create an adjustment invoice
- Step 1: The seller issues an electronic invoice to correct the incorrect invoice, then digitally signs it and sends it to the tax authority to issue a new invoice code to replace the invoice. In case the seller and buyer have agreed to draw up a written agreement before making an invoice to correct an invoice that has errors, the seller and buyer shall make a written agreement clearly stating the errors, then The seller issues an electronic invoice to adjust the invoice that has been created with errors. Electronic invoices to adjust electronic invoices that have been issued with errors must have the words "Adjustment for invoice Form number... symbol... number... date... month year".
- Step 2: Return the correct invoice to the buyer.
- Step 3: The seller shall notify the tax authority about the electronic invoice with errors according to Form No. 04/SS-HDĐT Appendix IA (except in cases where the electronic invoice does not have an error code from the tax authority). The above mentioned invoice data has not been sent to the tax authority).
Method 2: Create a replacement invoice
- Step 1: The seller issues a new electronic invoice to replace the erroneous electronic invoice, unless the seller and the buyer have agreed to draw up a written agreement before issuing an invoice to replace the existing invoice. If there are errors in the invoice, the seller and buyer will make a written agreement clearly stating the errors, then the seller will issue an electronic invoice to replace the invoice that was created with errors. The new electronic invoice to replace the electronic invoice that was created with errors must have the words "Replace for invoice Model number... symbol... number... date, month, year”
- Step 2: Send the invoice back to the buyer
- Step 3: The seller shall notify the tax authority about the electronic invoice with errors according to Form No. 04/SS-HDĐT Appendix IA (except in cases where the electronic invoice does not have an error code from the tax authority). The above mentioned invoice data has not been sent to the tax authority).
Note:
- According to Point a, Clause 1, Article 7 of Circular 78/2021/TT-BTC, taxpayers send a notice according to Form No. 04/SS-HDĐT to the tax authority. However, depending on the tax authority, it will not require sending in this case, the taxpayer needs to ask again to determine
- In case the issued electronic invoice has errors and the seller has handled it in the form of adjustment or replacement (as prescribed in Point b, Clause 2, Article 19 of Decree No. 123/2020/ND-CP), then If the seller discovers that the invoice continues to have errors, the seller will follow the method used when handling the errors for the first time.
- For errors in value content on the invoice: increase adjustment (record positive sign), decrease adjustment (record negative sign) in accordance with the actual adjustment.
- In cases where according to regulations, an electronic invoice is made without the invoice model number, invoice symbol, or invoice number with errors, the seller will only make adjustments without canceling or replacing.
· Case 4: The tax authority discovers that the electronic invoice with the tax authority's code or the electronic invoice without the tax authority's code has been created with errors.
Processing instructions:
- The tax authority notifies the seller according to Form No. 01/TB-RSDT Appendix IB issued with this Decree so that the seller can check for errors.
- According to the notification deadline stated on Form No. 01/TB RSĐT, Appendix IB, the seller shall notify the tax authority according to Form No. 04/SS-HDĐT in Appendix IA issued with this Decree regarding the inspection. The issued electronic invoice has errors, clearly stating that the basis for inspection is the notice of Form No. 01/TB-RSĐT from the tax authority (including information number and date of notification).
- After the notification period stated on Form No. 01/TB RSDT, Appendix IB, if the seller does not notify the tax authority, the tax authority will continue to notify the seller a second time according to Form No. 01/TB-RSDT, Appendix IB. . Past the time limit for the second notification recorded on Form No. 01/TB RSDT, Appendix IB, if the seller does not notify, the tax authority will consider switching to the case of checking the use of electronic invoices.
· Case 5: Invoices were prepared according to the provisions of Decree No. 51/2010/ND-CP dated May 14, 2010, Decree No. 04/2014/ND-CP dated January 17, 2014 of the Government and guiding documents of the Government. The Ministry of Finance made mistakes.
Processing instructions:
- Step 1: The seller and buyer must make a written agreement clearly stating the errors.
- Step 2: The seller notifies the tax authority according to Form No. 04/SS-HDĐT.
- Step 3: The seller issues an electronic invoice to replace the invoice that was created with errors (the invoice was created with errors according to Decree No. 51/2010/ND-CP, Decree No. 04/2014/ND -CP of the Government and guiding documents of the Ministry of Finance).
Then, the seller digitally signs the created replacement electronic invoice or (in case of using an electronic invoice without a code) or sends it to the tax authority to receive a code for the replacement electronic invoice. prepared (in case of using electronic invoices with tax authority codes). The electronic invoice to replace the invoice that was issued with errors must have the words "Replace for invoice Model number... symbol... number... date... month... year"
- Step 4: Send a replacement electronic invoice to the buyer.
Note:
Instructions for handling erroneous invoices in this case are specified in Clause 6, Article 12 of Circular 78/2021/TT-BTC.
NOTE: Currently, some tax departments require 4/SS-HDĐT to be submitted and approved before being allowed to cancel/replace/adjust. Please contact local tax officials for specific instructions. In case the issued electronic invoice has errors and the seller has handled it in the form of adjustment or replacement as prescribed in Point b, Clause 2, Article 19 of Decree No. 123/2020/ND-CP, then reissued the invoice. If the invoice continues to have errors, the seller will follow the method applied when handling the error for the first time.
Particularly for the content of value on the invoice with errors: adjust up (record positive sign), adjust down (record negative sign) in accordance with the actual adjustment. In cases where it is difficult to determine due to complex situations, Please contact your local tax official or CPA HCM specialist for specific instructions.
Tin cùng chuyên mục
CÔNG VĂN 8472/CT-QLNT: THUẾ TNCN 2% VÀ LỆ PHÍ TRƯỚC BẠ 0,5% KHI CHUYỂN NHƯỢNG BẤT ĐỘNG SẢN
Ngày 06/11/2026, Cục Thuế ban hành Công văn số 8472/CT-QLNT hướng dẫn thuế thu nhập cá nhân và lệ phí...
11/11/2026
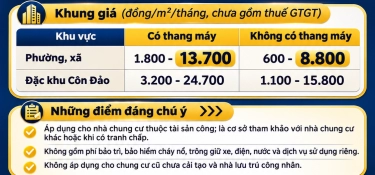
TP. HCM BAN HÀNH KHUNG GIÁ MỚI DỊCH VỤ QUẢN LÝ VẬN HÀNH NHÀ CHUNG CƯ, ÁP DỤNG TỪ 25/11/2026
Ngày 07/11/2026, UBND TP. HCM ban hành Quyết định số 96/2026/QĐ-UBND quy định khung giá dịch vụ quản lý...
11/11/2026
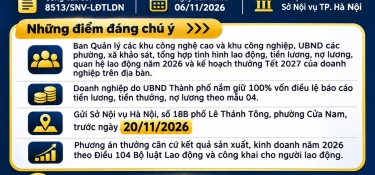
HÀ NỘI: BÁO CÁO TÌNH HÌNH TIỀN LƯƠNG, THƯỞNG TẾT 2027 TRƯỚC 20/11/2026
Ngày 06/11/2026, Sở Nội vụ TP. Hà Nội ban hành Công văn số 8513/SNV-LĐTLDN về việc báo cáo tình hình lao...
11/11/2026
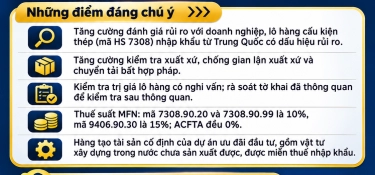
CẤU KIỆN THÉP, NHÀ TIỀN CHẾ NHẬP KHẨU: HẢI QUAN SIẾT KIỂM TRA TRỊ GIÁ, XUẤT XỨ
Ngày 06/11/2026, Cục Hải quan ban hành Công văn số 23969/CHQ-NVTHQ về quản lý rủi ro, kiểm tra xuất xứ và...
11/11/2026
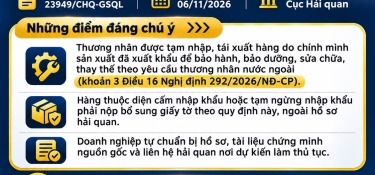
TẠM NHẬP HÀNG ĐÃ XUẤT KHẨU ĐỂ BẢO HÀNH, SỬA CHỮA: CHUẨN BỊ HỒ SƠ THẾ NÀO?
Ngày 06/11/2026, Cục Hải quan ban hành Công văn số 23949/CHQ-GSQL hướng dẫn thủ tục hải quan và tài liệu...
11/11/2026
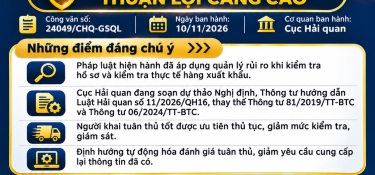
CỤC HẢI QUAN TRẢ LỜI KIẾN NGHỊ ĐƠN GIẢN HÓA KIỂM TRA HÀNG XUẤT KHẨU
Ngày 10/11/2026, Cục Hải quan ban hành Công văn số 24049/CHQ-GSQL trả lời kiến nghị của doanh nghiệp về...
11/11/2026
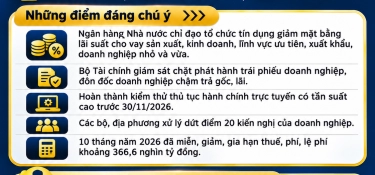
NGHỊ QUYẾT 353/NQ-CP: CHÍNH PHỦ YÊU CẦU TIẾP TỤC GIẢM LÃI SUẤT CHO VAY NHỮNG THÁNG CUỐI NĂM 2026
Ngày 06/11/2026, Chính phủ ban hành Nghị quyết số 353/NQ-CP phiên họp Chính phủ thường kỳ tháng 10/2026,...
11/11/2026
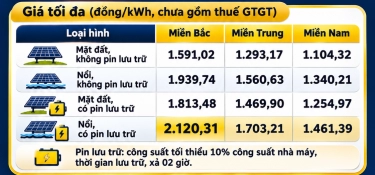
QUYẾT ĐỊNH 2946/QĐ-BCT: KHUNG GIÁ PHÁT ĐIỆN MẶT TRỜI NĂM 2026 CAO NHẤT 2.120,31 ĐỒNG/kWh
Ngày 05/11/2026, Bộ Công Thương ban hành Quyết định số 2946/QĐ-BCT phê duyệt khung giá phát điện loại...
11/11/2026
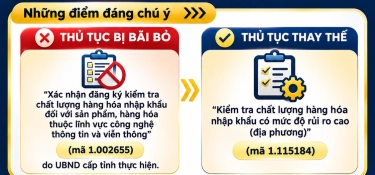
BÃI BỎ THỦ TỤC XÁC NHẬN ĐĂNG KÝ KIỂM TRA CHẤT LƯỢNG HÀNG NHẬP KHẨU CÔNG NGHỆ THÔNG TIN, VIỄN THÔNG
Ngày 03/11/2026, Bộ Khoa học và Công nghệ ban hành Quyết định số 4331/QĐ-BKHCN công bố thủ tục hành...
11/11/2026
THÔNG TƯ 57/2026/TT-NHNN: QUY TRÌNH GIÁM SÁT PHÒNG, CHỐNG RỬA TIỀN ÁP DỤNG TỪ 01/12/2026
Ngày 30/10/2026, Ngân hàng Nhà nước ban hành Thông tư số 57/2026/TT-NHNN quy định trình tự, thủ tục giám...
11/11/2026
REGISTER FOR WORKERSREGISTER OF RECRUITMENT
Most Viewed News
[HỘI THẢO ONLINE ]: CHI PHÍ LƯƠNG ĐƯỢC TRỪ KHI TÍNH THUẾ TNDN THEO NGHỊ ĐỊNH 320/2025/NĐ-CP
15/01/2026
Năm 2025 khép lại với những thay đổi chóng...
"TOP 20 EXCELLENT ENTERPRISES IN 2024" CPA HO CHI MINH CITY AFFIRMS ITS LEADING POSITION IN THE ACCOUNTING AND AUDITING INDUSTRY
21/08/2024
In a year full of changes, CPA HCM Audit &...
CPA HCM Training Academy continues to welcome more than 500 students from Ho Chi Minh City College of Economics.
16/06/2023
What benefits will you get from this course?
FOR THE FIRST TIME SIU STUDENTS LEARN FORMAL ACCOUNTING PRACTICE IN A BUSINESS ENVIRONMENT
05/04/2024
CPA HCM AUDIT & CONSULTING COMPANY LIMITED is...
SHORT THE ROAD TO SUCCESS WITH THE COURSE "GENERAL ACCOUNTING"
08/05/2024
You have accounting knowledge but feel it is not...
© All rights and copyrights belong to CPA HCM Audit and Advisory Company Limited Designed by
IMS