OFFICIAL RESPONSE ON THE GENERAL TAXATION'S REGULATION ON CALCULATION OF LATE TAX PAYMENT AREA
15:45:5602/06/2021
Regulations on calculating late payment interest for temporary tax payment are determined according to the time of the enterprise's fourth quarter tax payment deadline, accordingly, in case the total amount of tax temporarily paid in the tax period is lower than the amount of corporate income tax payable according to the tax period. If the settlement amount is 20% or more, the enterprise will pay late payment interest with the difference of 20% or more between the temporarily paid tax amount and the tax amount payable according to the settlement calculated from the day following the last day of the fourth quarter tax payment deadline. of the enterprise until the date of actual payment of the outstanding tax amount compared to the final tax amount.
Regulations on calculating late payment interest for temporary tax payment are determined according to the time of the enterprise's fourth quarter tax payment deadline, accordingly, in case the total amount of tax temporarily paid in the tax period is lower than the amount of corporate income tax payable according to the tax period. If the settlement amount is 20% or more, the enterprise will pay late payment interest with the difference of 20% or more between the temporarily paid tax amount and the tax amount payable according to the settlement calculated from the day following the last day of the fourth quarter tax payment deadline. of the enterprise until the date of actual payment of the outstanding tax amount compared to the final tax amount.
However, reality shows that many businesses not only do not comply but also deliberately take advantage of this regulation, leading to budget imbalance..
To solve the above problem, the Government issued Decree 126/2020/ND-CP effective from December 5, 2020, guiding the Law on Tax Administration, which stipulates the calculation of late payment interest for With regard to CIT temporarily paid during the year, the year-end finalization declaration has been amended at Point b, Clause 6, Article 8. Accordingly, in case the taxpayer underpays the amount of tax temporarily paid in the first 3 quarters of the year, he/she must pay money. Late payment is calculated on the amount of tax underpaid compared to the amount of tax payable according to finalization from the day following the last day of the temporary payment deadline for third quarter CIT to the date of payment of the outstanding tax amount to the state budget. This regulation comes from the fact that businesses have annual plans and plans for production and business activities, and will be completely proactive in determining/estimating the results of production and business activities to make temporary tax payments.
Tin cùng chuyên mục
HỘI THẢO ONLINE: THUẾ CHO TIKTOK CREATOR 2026 – CHỌN ĐÚNG PHƯƠNG ÁN, NỘP THUẾ TỐI ƯU
Cùng một quy mô doanh thu 2 tỷ đồng, tại sao có nhà sáng tạo chỉ nộp khoảng 95 triệu đồng, trong khi...
12/10/2026
TikTok Creator Tax Check 2026: Gỡ Rối Toàn Diện Nghĩa Vụ Thuế Cùng Chuyên Gia CPA HCM
Sự bùng nổ của nền kinh tế sáng tạo số đã biến công việc TikTok Creator, KOC và Streamer thành ngành...
30/09/2026
Ứng Dụng CPA HCM Tax360: Giải Pháp Quản Trị Rủi Ro Thuế Và Sức Khỏe Tài Chính Cho Doanh Nghiệp
1. Thực trạng quản trị thuế tại doanh nghiệp: Khi rủi ro đến từ sự thiếu chủ động
Trong hoạt...
23/09/2026
TỌA ĐÀM BQT CHUNG CƯ TP.HCM CPA HCM ĐỒNG HÀNH GIẢI BÀI TOÁN MINH BẠCH TÀI CHÍNH VÀ AN TOÀN PHÁP LÝ CHO NHÀ CHUNG CƯ
Ngày 19/09/2026 vừa qua, tại Hội trường Tòa nhà Viettel Tower (Quận 10, TP.HCM), chương trình chuyên đề...
23/09/2026
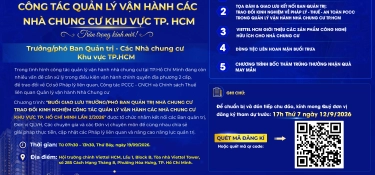
CHƯƠNG TRÌNH GIAO LƯU TRAO ĐỔI KINH NGHIỆM QUẢN LÝ VẬN HÀNH CÁC NHÀ CHUNG CƯ KHU VỰC TP.HCM LẦN 2/2026
Hiện nay, công tác quản lý vận hành (QLVH) nhà chung cư tại TP. Hồ Chí Minh đang đối mặt với nhiều...
07/09/2026
KẾ TOÁN XÂY DỰNG
Trong hệ thống kế toán doanh nghiệp, kế toán xây lắp (xây dựng) luôn được xếp vào nhóm nghiệp vụ...
02/07/2026
NGHỊ ĐỊNH 141/2026/NĐ-CP: NÂNG NGƯỠNG MIỄN THUẾ 1 TỶ ĐỒNG VÀ NHỮNG TÁC ĐỘNG THỰC TIỄN ĐẾN HỘ KINH DOANH, DOANH NGHIỆ
Ngày 29/04/2026, Chính phủ chính thức ban hành Nghị định 141/2026/NĐ-CP sửa đổi, bổ sung Nghị định...
12/05/2026
Quy trình kiểm toán nhà chung cư và những thời điểm bắt buộc thực hiện
Trong công tác quản lý vận hành nhà chung cư, tính minh bạch tài chính là yếu tố then chốt để duy trì...
12/05/2026
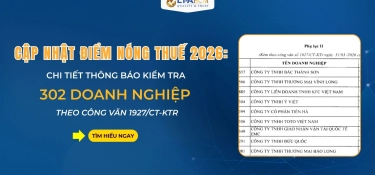
CẬP NHẬT ĐIỂM NÓNG THUẾ 2026: CHI TIẾT THÔNG BÁO KIỂM TRA 302 DOANH NGHIỆP THEO CÔNG VĂN 1927/CT-KTR
Ngày 31/03/2026, Cục Thuế đã ban hành Công văn số 1927/CT-KTr về việc tăng cường quản lý thuế đối...
11/05/2026
REGISTER FOR WORKERSREGISTER OF RECRUITMENT
Most Viewed News
[HỘI THẢO ONLINE ]: CHI PHÍ LƯƠNG ĐƯỢC TRỪ KHI TÍNH THUẾ TNDN THEO NGHỊ ĐỊNH 320/2025/NĐ-CP
15/01/2026
Năm 2025 khép lại với những thay đổi chóng...
"TOP 20 EXCELLENT ENTERPRISES IN 2024" CPA HO CHI MINH CITY AFFIRMS ITS LEADING POSITION IN THE ACCOUNTING AND AUDITING INDUSTRY
21/08/2024
In a year full of changes, CPA HCM Audit &...
CPA HCM Training Academy continues to welcome more than 500 students from Ho Chi Minh City College of Economics.
16/06/2023
What benefits will you get from this course?
FOR THE FIRST TIME SIU STUDENTS LEARN FORMAL ACCOUNTING PRACTICE IN A BUSINESS ENVIRONMENT
05/04/2024
CPA HCM AUDIT & CONSULTING COMPANY LIMITED is...
SHORT THE ROAD TO SUCCESS WITH THE COURSE "GENERAL ACCOUNTING"
08/05/2024
You have accounting knowledge but feel it is not...
© All rights and copyrights belong to CPA HCM Audit and Advisory Company Limited Designed by
IMS