4 SKILLS STEPS FOR ACCOUNTANTS
14:43:5801/06/2021
Indispensable skills for a new accountant or even for a long-time accountant
- Step 01: Determine the type of enterprise (DN)
-If it is a Manufacturing enterprise: This enterprise is required to calculate costs.
=> Gather production costs to calculate production costs such as completed products and unfinished products; Finished products are warehoused using account 155: Finished products.
- If you are a Commercial Enterprise: The characteristic of a Commercial Enterprise is buying and reselling => So you must understand how to calculate ex-warehouse prices, discounts, rebates, promotions, returned goods,...
=> This type does not calculate cost, so all operations are concentrated in inventory account 156
- If you are a Construction Enterprise: Must understand and know how to read estimates; Calculate detailed costs for each construction project object, time of acceptance and issuance of invoices,…
=> Gathered in Account 6 such as A/C 621, 622, 627 and transferred to A/C 154 ≥ A/C 632.
- Step 02: Arrange documents.
- Arrange and close Tax declaration books.
- Arrange output and input invoices according to the following methods: Invoice number ascending, alphabetically, by date,…
- Income and expenditure documents.
- Economic contracts.
- Insurance documents and labor records.
- Documents submitted to the state budget.
- Other documents.
- Invoices according to the Tax Declaration have been submitted respectively according to the Sales and Purchase Appendices during the declaration period.
- Print the entire tax return & Notice of successful electronic tax payment.
- Input invoices in the order of the Tax Declaration: Arranged in the order of the Declaration = Order of Red Lien input invoices by Month/Quarter.
- Output invoices in the order of the tax declaration: Arrange in the order of the declaration = Order of output invoices in the Green sheet according to the Month/Quarter period.
- Consider the elements of the invoice: Reasonability and validity of documents such as "Enterprise information; Commodity content,…”.
- Step 03: Prepare accounting books.
- Bookkeeping process: Invoices => General journal => Ledger => Balance of arising => Accounting records, business results, LCTT.
- Accounting for economic operations.
- Check the legality of the invoice: Reasonableness, validity, legality.
- Understand the nature of transactions arising from input invoices and documents.
- Classification of objects: Which objects are costs; Which object is revenue; Which objects are the revenues, expenses, etc. Each object has a complete set of accompanying documents.
- Enter documents into the software, calculate accurate and complete accounts, transfer final accounting entries => To generate profit and loss from production and business activities.
- Balance profit and loss, balance revenue versus costs, calculate costs, balance profit and loss with production costs,…
- Step 04: Close the books and prepare financial statements.
4.1. It is necessary to carefully review the economic operations and expenses incurred, and fully check the records:
- Check whether debts are accounted for by the wrong object?
- See if inventory elements are correct, negative, or different?
- Check whether expenses correspond to revenue?
- See factors about cash and deposits?
- See loan factors?
- See cost factors?
- See wage labor factors?
- Check for other unusual factors?
4.2. After the books are completed => Based on the data compiled from the soft FILE, you can prepare the financial statements according to regulations.
4.3. Full financial reports include:
- Balance sheet Form No. B01-DN.
- Report on business results Form No. B02-DN.
- Cash flow statement Form No. B03-DN.
- Explanation of financial statements Form No. B09-DN.
- Corporate income tax and personal income tax finalization declaration.
Tin cùng chuyên mục
CÔNG VĂN 8871/CT-QLNT: KHOẢN THU KHÔNG LIÊN QUAN BÁN HÀNG KHÔNG PHẢI LẬP HÓA ĐƠN ĐIỆN TỬ
Ngày 18/11/2026, Cục Thuế ban hành Công văn số 8871/CT-QLNT trả lời Thuế tỉnh Thái Nguyên: cơ sở kinh...
20/11/2026
CÔNG VĂN 24185/CHQ-NVTHQ: NƯỚC GIẢI KHÁT CÓ ĐƯỜNG TRÊN 5G/100ML CHỊU THUẾ TTĐB, KHÔNG ĐƯỢC GIẢM THUẾ GTGT
Ngày 12/11/2026, Cục Hải quan ban hành Công văn số 24185/CHQ-NVTHQ hướng dẫn chính sách thuế đối với...
20/11/2026
CÔNG VĂN 24424/CHQ-NVTHQ: THÁP ĐIỆN GIÓ NHẬP KHẨU TẠO TÀI SẢN CỐ ĐỊNH CÓ ĐƯỢC MIỄN THUẾ CHỐNG BÁN PHÁ GIÁ?
Ngày 18/11/2026, Cục Hải quan ban hành Công văn số 24424/CHQ-NVTHQ trả lời vướng mắc về thuế chống bán...
20/11/2026
CÔNG VĂN 8726/CT-QLNT: CHỦ SỞ HỮU HƯỞNG LỢI VÀ GIAO DỊCH LIÊN KẾT XÁC ĐỊNH THEO QUY ĐỊNH NÀO?
Ngày 13/11/2026, Cục Thuế ban hành Công văn số 8726/CT-QLNT trả lời kiến nghị của một công ty luật về...
19/11/2026
HÀNG KHÔNG VÀO NỘI ĐỊA VIỆT NAM KHÔNG CHỊU THUẾ GTGT: BÁN HÀNG TRONG KHO NGOẠI QUAN VÀ BÁN QUA SÀN NƯỚC NGOÀI
Thuế thành phố Hà Nội (Công văn số 52537/HAN-QLDN3 ngày 27/10/2026) và Thuế cơ sở 6 thành phố Hà Nội...
19/11/2026
CÔNG VĂN 52607/HAN-QLDN4: AI LẬP HÓA ĐƠN, AI NỘP THUẾ GTGT KHI THU PHÍ KHÔNG DỪNG TẠI BẾN XE, BÃI ĐỖ?
Ngày 27/10/2026, Thuế thành phố Hà Nội ban hành Công văn số 52607/HAN-QLDN4 hướng dẫn việc lập hóa đơn...
19/11/2026
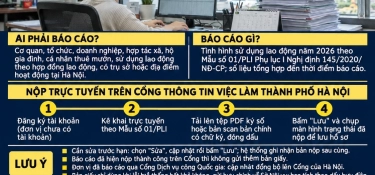
CÔNG VĂN 8865/SNV-VLATLĐ: DOANH NGHIỆP TẠI HÀ NỘI BÁO CÁO SỬ DỤNG LAO ĐỘNG NĂM 2026 TRƯỚC 05/12
Ngày 17/11/2026, Sở Nội vụ thành phố Hà Nội ban hành Công văn số 8865/SNV-VLATLĐ về việc báo cáo tình...
19/11/2026
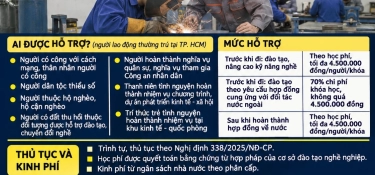
NGHỊ QUYẾT 92/2026/NQ-HĐND: LAO ĐỘNG TP. HCM ĐI LÀM VIỆC Ở NƯỚC NGOÀI ĐƯỢC HỖ TRỢ HỌC NGHỀ ĐẾN 4.500.000 ĐỒNG
Ngày 30/10/2026, HĐND Thành phố Hồ Chí Minh ban hành Nghị quyết số 92/2026/NQ-HĐND quy định hỗ trợ đào...
19/11/2026
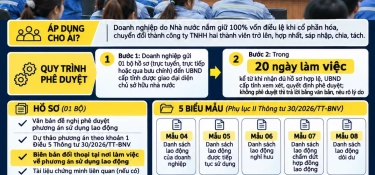
QUYẾT ĐỊNH 1405/QĐ-BNV: THỦ TỤC PHÊ DUYỆT PHƯƠNG ÁN SỬ DỤNG LAO ĐỘNG KHI CƠ CẤU LẠI DOANH NGHIỆP 100% VỐN NHÀ NƯỚC
Ngày 13/11/2026, Bộ Nội vụ ban hành Quyết định số 1405/QĐ-BNV về thủ tục phê duyệt phương án sử...
19/11/2026
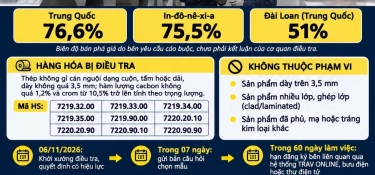
QUYẾT ĐỊNH 2948/QĐ-BCT: ĐIỀU TRA CHỐNG BÁN PHÁ GIÁ THÉP KHÔNG GỈ CÁN NGUỘI NHẬP KHẨU
Ngày 06/11/2026, Bộ Công Thương ban hành Quyết định số 2948/QĐ-BCT khởi xướng điều tra chống bán phá...
19/11/2026
REGISTER FOR WORKERSREGISTER OF RECRUITMENT
Most Viewed News
[HỘI THẢO ONLINE ]: CHI PHÍ LƯƠNG ĐƯỢC TRỪ KHI TÍNH THUẾ TNDN THEO NGHỊ ĐỊNH 320/2025/NĐ-CP
15/01/2026
Năm 2025 khép lại với những thay đổi chóng...
"TOP 20 EXCELLENT ENTERPRISES IN 2024" CPA HO CHI MINH CITY AFFIRMS ITS LEADING POSITION IN THE ACCOUNTING AND AUDITING INDUSTRY
21/08/2024
In a year full of changes, CPA HCM Audit &...
CPA HCM Training Academy continues to welcome more than 500 students from Ho Chi Minh City College of Economics.
16/06/2023
What benefits will you get from this course?
FOR THE FIRST TIME SIU STUDENTS LEARN FORMAL ACCOUNTING PRACTICE IN A BUSINESS ENVIRONMENT
05/04/2024
CPA HCM AUDIT & CONSULTING COMPANY LIMITED is...
SHORT THE ROAD TO SUCCESS WITH THE COURSE "GENERAL ACCOUNTING"
08/05/2024
You have accounting knowledge but feel it is not...
© All rights and copyrights belong to CPA HCM Audit and Advisory Company Limited Designed by
IMS