CONSTRUCTION ACCOUNTING
09:27:5526/02/2021
CONSTRUCTION ACCOUNTING
“CPA HCM always updates and brings you the latest and most accurate news”
CONSTRUCTION ACCOUNTING NOTES - CONSTRUCTION AND INSTALLATION
+ Error 1: The project has been accepted, but due to some reasons we cannot issue an invoice. For example: Party A hasn't paid yet so the boss won't let it go. With this error, we will have our revenue and VAT returned at the time of acceptance.
+ Error 2: The input of raw materials and labor does not match the estimate, because the materials and labor are loaded by the accountant based on emotion. And it leads to:
- The cost of raw materials included is higher than the total level of raw materials in the total budget items of the estimate.
- Salary costs are higher than the total labor level in the total budget items of the old estimate
- General production costs included are higher than the total general production costs in the total budget items of the estimate.
- The cost of construction machines included is higher than the total cost of construction machines in the total cost of each category of the estimate..
+ Error 3: Raw materials are taken after the acceptance date but are still included as expenses when there are not enough procedures to protect them. To protect you need:
- Contract
- Goods handover record "The date on the record is the day before acceptance and the record is numbered
+ Error 4: I see a lot of companies with CTrinh have stopped construction but still calculate time and salary and still include costs, or I see some companies have time and salary calculation but no one signs. Even still depreciate and allocate construction machinery costs.
- The remuneration of the Board of Directors for members of the Board of Directors must be accompanied by a meeting minutes of the Board of Directors agreeing to appoint those members to directly participate in the operations of the enterprise or if it is a concurrent remuneration of a member of the Board of Directors. should be added to the salary to rationalize.
+ Error 5: Not separately tracking the costs of each project, raw materials, labor, and production are aggregated into one at the end of the month without distinguishing which project it belongs to, making it difficult to know when asked by tax. Which project does it belong to?
+ Error 6: With the cost of construction machines, almost small companies do not have oil norms for machine shifts and do not have vehicle mobilization schedules.
+ Error 7: The food bill the bosses brought home did not come with a bill. Or there is a case where the boss has a receipt for buying supplies from a supermarket...the boss buys it but brings it back to the accountant for tax declaration and is disbursed, not accepting the cost and deducting VAT.
- Electricity and water costs for borrowed offices (not rented offices) but not under the company's name. Therefore, it is necessary to rationalize by renting an office at a low price and paying taxes if the electricity and water costs are large.
+ Error 8: Too much negative cash fund, there is no negative cash balance, negative bank deposits. Or collect cash and record debt, buy debt and record cash collection. This man's beard sticks to that woman's chin.
- I have a lot of cash to borrow from the bank, so loan repayment is not accepted.
+ Error 9: Loans from individuals that exceed 150% of the basic interest rate prescribed by the State Bank will be eliminated, so it is necessary to rationalize by increasing the loan principal to reduce interest rates down.
+ Error 10: In case of signing a contract to purchase raw materials without the unit having a warehouse and writing a one-time invoice at the end of the month with a large value, the payment must be accompanied by additional detailed documents. Additional information such as: delivery note from the seller each time the unit picks up goods, a list of each day of receipt of goods signed by the seller and confirmed by the buyer. . . then the cost is reasonable.
+ Error 11: It's about the books
- There is no summary table of debts and detailed debts.
- There is no detailed raw materials book, no summary table of import and export inventory.
- Assets purchased without invoices or documents are still depreciated and allocated.
- Failure to pay license tax on time will result in late payment penalty.
- Failure to pay VAT and CIT on time with late payment penalty.
AND IF YOU WANT TO BE ACCURATE, REMEMBER TO GO TO CPA HCM!!!
Tin cùng chuyên mục
CÔNG VĂN 8472/CT-QLNT: THUẾ TNCN 2% VÀ LỆ PHÍ TRƯỚC BẠ 0,5% KHI CHUYỂN NHƯỢNG BẤT ĐỘNG SẢN
Ngày 06/11/2026, Cục Thuế ban hành Công văn số 8472/CT-QLNT hướng dẫn thuế thu nhập cá nhân và lệ phí...
11/11/2026
TP. HCM BAN HÀNH KHUNG GIÁ MỚI DỊCH VỤ QUẢN LÝ VẬN HÀNH NHÀ CHUNG CƯ, ÁP DỤNG TỪ 25/11/2026
Ngày 07/11/2026, UBND TP. HCM ban hành Quyết định số 96/2026/QĐ-UBND quy định khung giá dịch vụ quản lý...
11/11/2026
HÀ NỘI: BÁO CÁO TÌNH HÌNH TIỀN LƯƠNG, THƯỞNG TẾT 2027 TRƯỚC 20/11/2026
Ngày 06/11/2026, Sở Nội vụ TP. Hà Nội ban hành Công văn số 8513/SNV-LĐTLDN về việc báo cáo tình hình lao...
11/11/2026
CẤU KIỆN THÉP, NHÀ TIỀN CHẾ NHẬP KHẨU: HẢI QUAN SIẾT KIỂM TRA TRỊ GIÁ, XUẤT XỨ
Ngày 06/11/2026, Cục Hải quan ban hành Công văn số 23969/CHQ-NVTHQ về quản lý rủi ro, kiểm tra xuất xứ và...
11/11/2026
TẠM NHẬP HÀNG ĐÃ XUẤT KHẨU ĐỂ BẢO HÀNH, SỬA CHỮA: CHUẨN BỊ HỒ SƠ THẾ NÀO?
Ngày 06/11/2026, Cục Hải quan ban hành Công văn số 23949/CHQ-GSQL hướng dẫn thủ tục hải quan và tài liệu...
11/11/2026
CỤC HẢI QUAN TRẢ LỜI KIẾN NGHỊ ĐƠN GIẢN HÓA KIỂM TRA HÀNG XUẤT KHẨU
Ngày 10/11/2026, Cục Hải quan ban hành Công văn số 24049/CHQ-GSQL trả lời kiến nghị của doanh nghiệp về...
11/11/2026
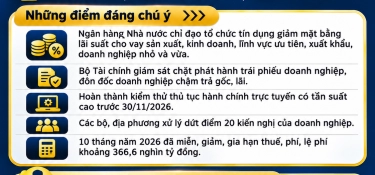
NGHỊ QUYẾT 353/NQ-CP: CHÍNH PHỦ YÊU CẦU TIẾP TỤC GIẢM LÃI SUẤT CHO VAY NHỮNG THÁNG CUỐI NĂM 2026
Ngày 06/11/2026, Chính phủ ban hành Nghị quyết số 353/NQ-CP phiên họp Chính phủ thường kỳ tháng 10/2026,...
11/11/2026
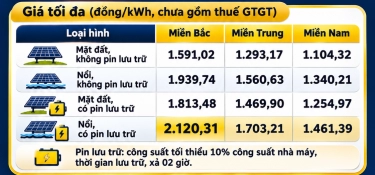
QUYẾT ĐỊNH 2946/QĐ-BCT: KHUNG GIÁ PHÁT ĐIỆN MẶT TRỜI NĂM 2026 CAO NHẤT 2.120,31 ĐỒNG/kWh
Ngày 05/11/2026, Bộ Công Thương ban hành Quyết định số 2946/QĐ-BCT phê duyệt khung giá phát điện loại...
11/11/2026
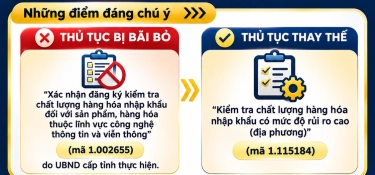
BÃI BỎ THỦ TỤC XÁC NHẬN ĐĂNG KÝ KIỂM TRA CHẤT LƯỢNG HÀNG NHẬP KHẨU CÔNG NGHỆ THÔNG TIN, VIỄN THÔNG
Ngày 03/11/2026, Bộ Khoa học và Công nghệ ban hành Quyết định số 4331/QĐ-BKHCN công bố thủ tục hành...
11/11/2026
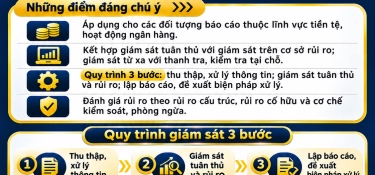
THÔNG TƯ 57/2026/TT-NHNN: QUY TRÌNH GIÁM SÁT PHÒNG, CHỐNG RỬA TIỀN ÁP DỤNG TỪ 01/12/2026
Ngày 30/10/2026, Ngân hàng Nhà nước ban hành Thông tư số 57/2026/TT-NHNN quy định trình tự, thủ tục giám...
11/11/2026
REGISTER FOR WORKERSREGISTER OF RECRUITMENT
Most Viewed News
[HỘI THẢO ONLINE ]: CHI PHÍ LƯƠNG ĐƯỢC TRỪ KHI TÍNH THUẾ TNDN THEO NGHỊ ĐỊNH 320/2025/NĐ-CP
15/01/2026
Năm 2025 khép lại với những thay đổi chóng...
"TOP 20 EXCELLENT ENTERPRISES IN 2024" CPA HO CHI MINH CITY AFFIRMS ITS LEADING POSITION IN THE ACCOUNTING AND AUDITING INDUSTRY
21/08/2024
In a year full of changes, CPA HCM Audit &...
CPA HCM Training Academy continues to welcome more than 500 students from Ho Chi Minh City College of Economics.
16/06/2023
What benefits will you get from this course?
FOR THE FIRST TIME SIU STUDENTS LEARN FORMAL ACCOUNTING PRACTICE IN A BUSINESS ENVIRONMENT
05/04/2024
CPA HCM AUDIT & CONSULTING COMPANY LIMITED is...
SHORT THE ROAD TO SUCCESS WITH THE COURSE "GENERAL ACCOUNTING"
08/05/2024
You have accounting knowledge but feel it is not...
© All rights and copyrights belong to CPA HCM Audit and Advisory Company Limited Designed by
IMS