Process for processing requests for extension of tax payment and land rent payment in 2021
10:17:5301/06/2021
To support taxpayers who request to extend tax payment and land rent payment in 2021 in accordance with the provisions of Decree No. 52/2021/ND-CP, the General Department of Taxation has just issued a document guiding tax authorities at all levels. Process for processing taxpayer extension requests.
According to the General Department of Taxation, based on the information on the taxpayer's request for extension that has been updated according to the instructions of the Tax authority, the Centralized Tax Management Application System (TMS) will process as follows:
For requests for extension of value-added tax (VAT) payment: The TMS system automatically updates the extended tax payment deadline for the arising VAT payable of the tax period of March, April, and December. 5, June, July, August 2021 and the tax period of the first quarter, second quarter of 2021 according to Form 01/GTGT, 03/GTGT, 04/GTGT, 05/GTGT (including official declaration and added during the extended period).
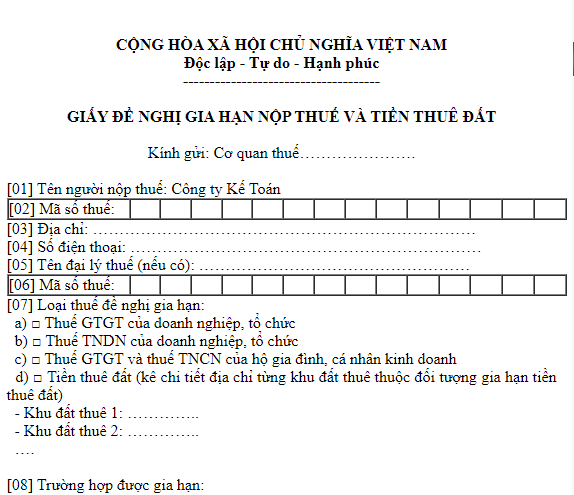
For the VAT amount extended according to appendix Form 01-6/GTGT, the tax declaration and accounting department of the tax agency managing the allocated VAT amount will look up the list of proposed taxpayers. extension on the TMS system to control and update the extended tax payment deadline.
For requests for extension of corporate income tax (CIT) payment: Taxpayers self-determine the tax amount that must be temporarily paid in the first and second quarters of the 2021 corporate income tax period and based on the extended deadline as prescribed in Clause 1 of this Article. Clause 2, Article 3 of Decree No. 52/2021/ND-CP to pay money into the state budget.
For requests to extend payment of VAT and personal income tax (PIT) of households and individual businesses: The TMS system automatically updates the extended tax payment deadline for VAT and PIT amounts. arising payable in 2021 of households and individual businesses.
For the request to extend land rent payment: The taxpayer has accurately declared the notice number information; At the same time, the tax authority issued a land rent notice on the Extension Application and the tax authority fully updated the corresponding land rent notice number information on the TMS system. The TMS system will support automatic updating of land rent payment extension information according to each Notice for the land rent payable in the first period of 2021 as prescribed in Clause 4, Article 3 of Decree No. 52/2021/ND -CP.
In case the TMS system does not have enough information to support automatic updating, the tax authority managing land rent collections will look up the list of taxpayers requesting extension on TMS to review and update the information. Extension of land rent payment according to the Notice for land rent payable in the first period of 2021.
The General Department of Taxation also notes that in cases where the extension request is sent after the tax authority closes the monthly tax accounting book, the tax authority will manually update the extended payment deadline for the extended tax amount. In the period that has been closed, the TMS system automatically updates the payment deadline for the tax payable in the next extended tax periods. Tax authorities make adjustments to previously calculated late payment interest (if any).
In case during the extension period, the tax authority has a basis to determine that the taxpayer is not subject to the extension, the tax authority shall issue a notice to the taxpayer about stopping the extension according to the form prescribed by the General Department of Taxation. ; At the same time, require taxpayers to pay the full amount of tax, land rent and late payment interest during the extended period to the state budget.
After the extension period expires, through inspection and testing it is discovered that the taxpayer is not eligible for an extension to pay taxes and land rent according to regulations, the tax authority requires the taxpayer to pay the remaining tax amount. deficiency, fines and late payment interest are determined back into the state budget.
Tin cùng chuyên mục
CÔNG VĂN 8871/CT-QLNT: KHOẢN THU KHÔNG LIÊN QUAN BÁN HÀNG KHÔNG PHẢI LẬP HÓA ĐƠN ĐIỆN TỬ
Ngày 18/11/2026, Cục Thuế ban hành Công văn số 8871/CT-QLNT trả lời Thuế tỉnh Thái Nguyên: cơ sở kinh...
20/11/2026
CÔNG VĂN 24185/CHQ-NVTHQ: NƯỚC GIẢI KHÁT CÓ ĐƯỜNG TRÊN 5G/100ML CHỊU THUẾ TTĐB, KHÔNG ĐƯỢC GIẢM THUẾ GTGT
Ngày 12/11/2026, Cục Hải quan ban hành Công văn số 24185/CHQ-NVTHQ hướng dẫn chính sách thuế đối với...
20/11/2026
CÔNG VĂN 24424/CHQ-NVTHQ: THÁP ĐIỆN GIÓ NHẬP KHẨU TẠO TÀI SẢN CỐ ĐỊNH CÓ ĐƯỢC MIỄN THUẾ CHỐNG BÁN PHÁ GIÁ?
Ngày 18/11/2026, Cục Hải quan ban hành Công văn số 24424/CHQ-NVTHQ trả lời vướng mắc về thuế chống bán...
20/11/2026
CÔNG VĂN 8726/CT-QLNT: CHỦ SỞ HỮU HƯỞNG LỢI VÀ GIAO DỊCH LIÊN KẾT XÁC ĐỊNH THEO QUY ĐỊNH NÀO?
Ngày 13/11/2026, Cục Thuế ban hành Công văn số 8726/CT-QLNT trả lời kiến nghị của một công ty luật về...
19/11/2026
HÀNG KHÔNG VÀO NỘI ĐỊA VIỆT NAM KHÔNG CHỊU THUẾ GTGT: BÁN HÀNG TRONG KHO NGOẠI QUAN VÀ BÁN QUA SÀN NƯỚC NGOÀI
Thuế thành phố Hà Nội (Công văn số 52537/HAN-QLDN3 ngày 27/10/2026) và Thuế cơ sở 6 thành phố Hà Nội...
19/11/2026
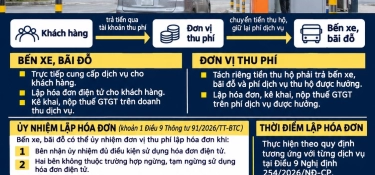
CÔNG VĂN 52607/HAN-QLDN4: AI LẬP HÓA ĐƠN, AI NỘP THUẾ GTGT KHI THU PHÍ KHÔNG DỪNG TẠI BẾN XE, BÃI ĐỖ?
Ngày 27/10/2026, Thuế thành phố Hà Nội ban hành Công văn số 52607/HAN-QLDN4 hướng dẫn việc lập hóa đơn...
19/11/2026
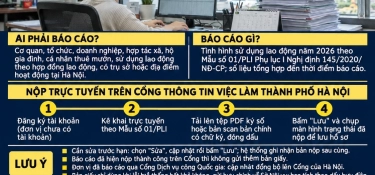
CÔNG VĂN 8865/SNV-VLATLĐ: DOANH NGHIỆP TẠI HÀ NỘI BÁO CÁO SỬ DỤNG LAO ĐỘNG NĂM 2026 TRƯỚC 05/12
Ngày 17/11/2026, Sở Nội vụ thành phố Hà Nội ban hành Công văn số 8865/SNV-VLATLĐ về việc báo cáo tình...
19/11/2026
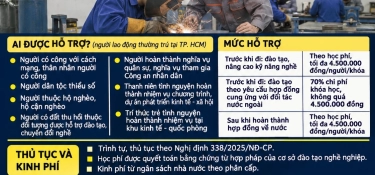
NGHỊ QUYẾT 92/2026/NQ-HĐND: LAO ĐỘNG TP. HCM ĐI LÀM VIỆC Ở NƯỚC NGOÀI ĐƯỢC HỖ TRỢ HỌC NGHỀ ĐẾN 4.500.000 ĐỒNG
Ngày 30/10/2026, HĐND Thành phố Hồ Chí Minh ban hành Nghị quyết số 92/2026/NQ-HĐND quy định hỗ trợ đào...
19/11/2026
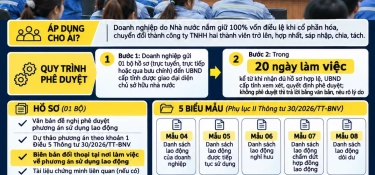
QUYẾT ĐỊNH 1405/QĐ-BNV: THỦ TỤC PHÊ DUYỆT PHƯƠNG ÁN SỬ DỤNG LAO ĐỘNG KHI CƠ CẤU LẠI DOANH NGHIỆP 100% VỐN NHÀ NƯỚC
Ngày 13/11/2026, Bộ Nội vụ ban hành Quyết định số 1405/QĐ-BNV về thủ tục phê duyệt phương án sử...
19/11/2026
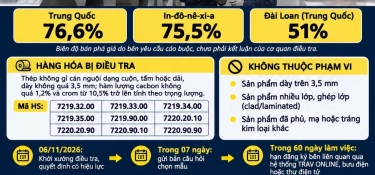
QUYẾT ĐỊNH 2948/QĐ-BCT: ĐIỀU TRA CHỐNG BÁN PHÁ GIÁ THÉP KHÔNG GỈ CÁN NGUỘI NHẬP KHẨU
Ngày 06/11/2026, Bộ Công Thương ban hành Quyết định số 2948/QĐ-BCT khởi xướng điều tra chống bán phá...
19/11/2026
REGISTER FOR WORKERSREGISTER OF RECRUITMENT
Most Viewed News
[HỘI THẢO ONLINE ]: CHI PHÍ LƯƠNG ĐƯỢC TRỪ KHI TÍNH THUẾ TNDN THEO NGHỊ ĐỊNH 320/2025/NĐ-CP
15/01/2026
Năm 2025 khép lại với những thay đổi chóng...
"TOP 20 EXCELLENT ENTERPRISES IN 2024" CPA HO CHI MINH CITY AFFIRMS ITS LEADING POSITION IN THE ACCOUNTING AND AUDITING INDUSTRY
21/08/2024
In a year full of changes, CPA HCM Audit &...
CPA HCM Training Academy continues to welcome more than 500 students from Ho Chi Minh City College of Economics.
16/06/2023
What benefits will you get from this course?
FOR THE FIRST TIME SIU STUDENTS LEARN FORMAL ACCOUNTING PRACTICE IN A BUSINESS ENVIRONMENT
05/04/2024
CPA HCM AUDIT & CONSULTING COMPANY LIMITED is...
SHORT THE ROAD TO SUCCESS WITH THE COURSE "GENERAL ACCOUNTING"
08/05/2024
You have accounting knowledge but feel it is not...
© All rights and copyrights belong to CPA HCM Audit and Advisory Company Limited Designed by
IMS